Africa’s 10 best airlines, and what the numbers reveal
- Business and Networking
- September 28, 2026
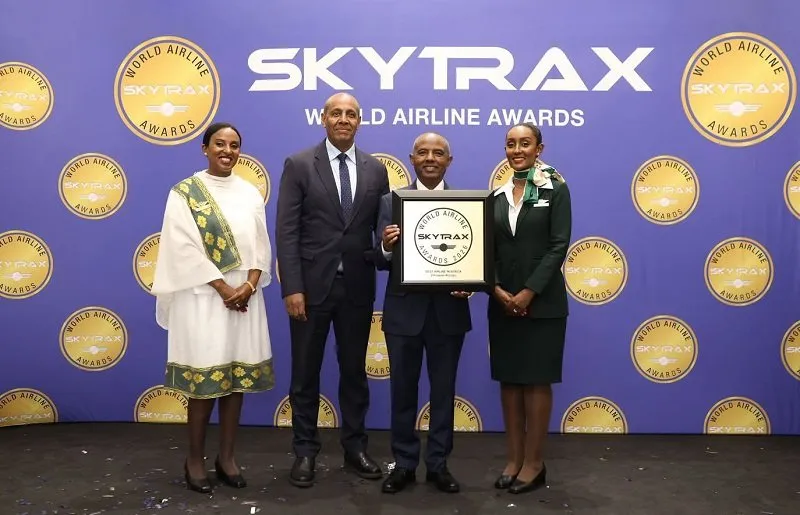

Ethiopian Airlines tops Skytrax’s 2026 African ranking and also stands out for its scale. But the ranking does not measure financial health: the available data reveal wide differences in size, investment and transparency.
LAGOS — Skytrax’s 2026 African airline ranking places Ethiopian Airlines first, followed by Egyptair and Air Mauritius. It is an airline ranking, not a measure of financial performance. It should not be interpreted as a comparison of profits, debt, punctuality or operating efficiency.
The financial figures below cover different reporting periods, and not all airlines publish comparable data. Where detailed accounts are unavailable, this limits the conclusions that can reasonably be drawn: a ranking position reflects passenger recognition, but does not, on its own, provide a reliable measure of the strength of the underlying business.
The ranking and the strategy behind each airline, 2026
| Skytrax | Airline | Country | Key data or strategic priority |
|---|---|---|---|
| 1 | Ethiopian Airlines | Ethiopia | US$7.6bn in revenue and 19mn passengers in 2024/25 |
| 2 | Egyptair | Egypt | Order for 16 Airbus A350-900s; fleet plan for 2030/31 |
| 3 | Air Mauritius | Mauritius | €599.4mn in revenue and €2mn profit in 2023/24 |
| 4 | Royal Air Maroc | Morocco | Target of 100 aircraft by 2030; expansion of Casablanca hub |
| 5 | RwandAir | Rwanda | Regional connectivity strategy; limited publicly available financial data |
| 6 | South African Airways | South Africa | R336mn operating profit in 2024/25 |
| 7 | Kenya Airways | Kenya | Net profit in 2024, followed by a loss in 2025 |
| 8 | FlySafair | South Africa | Low-cost carrier; no comparable public accounts available for this analysis |
| 9 | Fastjet | Zimbabwe | 274,000 passengers on its Zimbabwe operation in 2024 |
| 10 | LIFT | South Africa | More than four million passengers in its first five years |
The financial results relate to the reporting periods indicated and are not directly comparable. The order of the table follows Skytrax; the strategic notes do not constitute a second ranking.
1. Ethiopian Airlines: continental scale
Ethiopian Airlines tops both the Skytrax ranking and the comparison of scale among carriers for which recent data are available. In the 2024/25 financial year, it carried 19mn passengers and reported US$7.6bn in revenue, up from 17mn passengers a year earlier. The airline also said it took delivery of 13 aircraft and launched six international destinations during the period.
Scale helps underpin an extensive international network and operations across several segments, including cargo. But revenue and passenger volumes alone are insufficient to establish profitability or cost per seat. That would require standardised operating and financial metrics across all the carriers.
2. Egyptair: long-haul expansion
Egyptair, ranked second, is betting on fleet renewal and expansion. In 2025, Egypt’s Ministry of Civil Aviation announced an order for 10 Airbus A350-900 aircraft. Airbus subsequently confirmed an additional firm order for six, taking the publicly disclosed total to 16.
The airline has also set a target of 97 aircraft by 2030/31, compared with a fleet of 71 aircraft cited in 2025. The target illustrates the scale of the airline’s ambitions, but it should not be confused with capital already invested: deliveries, financing and entry into service may take place over several years.
3. Air Mauritius: higher revenue, thinner margin
Air Mauritius ranks third. In the 2023/24 financial year, revenue increased from €506mn to €599.4mn, while passenger numbers rose from approximately 1.33mn to 1.62mn. Profit, however, declined from €5.7mn to €2mn.
The airline took delivery of two Airbus A330-200s and one ATR-72-600 during the year, according to its annual report. Fleet expansion accompanied the recovery in traffic, but the gap between revenue growth and profit illustrates why scale should not be mistaken for profitability.
4. Royal Air Maroc: hub strategy and infrastructure
Royal Air Maroc ranks fourth. For the summer of 2025, it announced capacity of 6.6mn seats across more than 95 destinations. The Moroccan government has set a target of increasing the airline’s fleet from roughly 50 aircraft to 100 by 2030.
The airline’s expansion coincides with a public programme involving Dh38bn of investment in airport infrastructure through 2030. That amount relates to Morocco’s airports, rather than Royal Air Maroc itself. Airport infrastructure can support greater connectivity and tourism, but it should not be added to the airline’s aircraft orders or its own capital investment.
5. RwandAir: ambition, but limited financial disclosure
RwandAir ranks fifth. The airline and the Rwandan government are seeking to develop Kigali as a regional and international gateway. However, this analysis did not identify a recent, detailed public series of revenue, profit and passenger figures that would allow the carrier to be compared financially with Ethiopian Airlines, Air Mauritius, SAA or Kenya Airways.
Its fifth-place position can therefore be presented as recognition by Skytrax, but not as evidence that RwandAir is Africa’s fifth-largest or fifth-most profitable airline.
6. South African Airways: operational recovery
South African Airways, ranked sixth, reported R9.266bn in revenue for the financial year ended March 2025, compared with R7.029bn a year earlier. Operating profit reached R336mn, reversing an operating loss of R513mn. The airline carried 1.9mn passengers and recorded a scheduled-flight completion rate of 99.6 per cent.
The figures point to a recovery, but they should be interpreted cautiously. SAA carried roughly one-tenth of Ethiopian Airlines’ passenger volume in 2024/25. The airlines report on different fiscal periods, so the comparison is intended only to illustrate the difference in scale, rather than productivity.
7. Kenya Airways: recovery interrupted
Kenya Airways had a strong 2024, carrying 5.23mn passengers, generating KSh188.5bn in revenue and recording a KSh5.4bn net profit.
In 2025, revenue fell to KSh161.5bn, while the airline reported a KSh17.2bn loss. Its annual report points to lower capacity and passenger numbers; by year-end, the carrier operated 37 owned or leased aircraft.
The swing from profit to loss in a single year highlights the airline’s exposure to aircraft availability and its ability to maintain capacity. It also illustrates why financial performance cannot be inferred from a passenger-satisfaction ranking.
8. FlySafair: low-cost model, limited disclosure
FlySafair, ranked eighth, operates a low-cost model that differs from network carriers such as Ethiopian Airlines and Kenya Airways. The airline has published information on its operations and workforce, including an announcement that it had 1,800 employees when it reached an agreement to end a pilots’ strike in August 2025, but this analysis did not identify recent publicly available financial statements that would allow revenue, margins and investment to be compared with the carriers above.
Without that information, its market positioning can be described, but there is insufficient evidence to conclude that the airline is financially more efficient or profitable than its peers.
9. Fastjet: smaller-scale operation
Fastjet ranks ninth. The company says its Zimbabwe operation has carried more than 1.9mn passengers since launchand connects Zimbabwean cities with destinations in South Africa.
Fastjet Group’s 2024 annual report showed higher consolidated revenue and a return to profitability. Those figures cover other operations within the group and therefore should not be attributed exclusively to the Zimbabwean airline operation.
10. LIFT: young and focused on the domestic market
LIFT rounds out the list. The airline says it has carried more than four million passengers and completed more than 30,000 flights during its first five years. These are cumulative figures since the carrier began operations, rather than results for a single financial year.
The figures provide a useful indication of the carrier’s growth, but they are no substitute for annual accounts. Without comparable data on revenue, profit, debt and investment, its economic scale cannot be assessed against the larger network airlines.
What the ranking tells us
Ethiopian Airlines combines the top Skytrax position with the largest demonstrated scale among the carriers covered by the available data. Egyptair and Royal Air Maroc have significant expansion plans; Air Mauritius has recorded a recovery in traffic and revenue, albeit with lower profit; while SAA and Kenya Airways show markedly different financial trajectories, a recovery in one case and a reversal in the other.
For the remaining carriers, uneven financial disclosure prevents a rigorous comparison of economic performance. The most defensible conclusion is therefore a limited one, Skytrax measures passenger experience; financial statements provide evidence of scale and performance; and fleet announcements indicate future plans rather than necessarily representing capital already invested.
A meaningful comparison of continental competitiveness would require harmonised data on operating margins, debt, cost per seat, load factors, punctuality and executed investment.