Africa’s five largest banks hold $835bn in assets as South Africa dominates 2026 rankings
- Business and NetworkingEgyptSouth Africa
- November 16, 2026
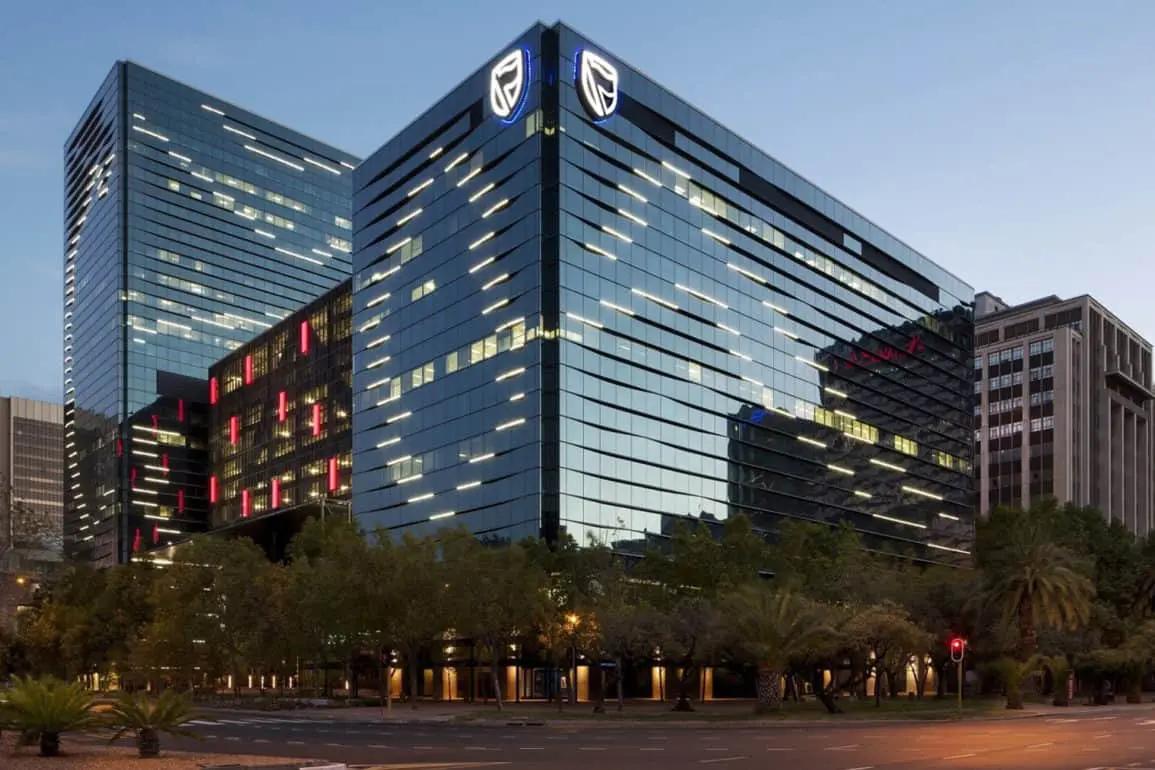

Standard Bank leads the continent’s banking industry, followed by National Bank of Egypt, FirstRand, Absa and Nedbank. South African lenders account for more than 76 per cent of the combined assets of the five largest institutions, highlighting the concentration of financial power in Africa’s most developed banking market.
LAGOS — Africa’s five largest banks held approximately $835bn in combined assets at the end of June 2026, with South African institutions occupying four of the top five positions, according to a ranking published by Egyptian financial information platform First Bank.
Standard Bank Group retained its continental leadership with $232.27bn in assets, followed by National Bank of Egypt at $197.98bn. FirstRand ranked third with $167.31bn, ahead of Absa Group at $139.23bn and Nedbank at $98.21bn.
The figures underscore the dominance of South Africa’s banking industry, supported by deep capital markets, diversified funding sources and established cross-border operations. They also highlight Egypt’s position as a major financial centre, with its largest state-owned lender holding nearly $198bn in assets.
Africa’s five largest banks in 2026
| Rank | Bank | Country | Total assets |
|---|---|---|---|
| 1 | Standard Bank Group | South Africa | $232.27bn |
| 2 | National Bank of Egypt | Egypt | $197.98bn |
| 3 | FirstRand | South Africa | $167.31bn |
| 4 | Absa Group | South Africa | $139.23bn |
| 5 | Nedbank Group | South Africa | $98.21bn |
Standard Bank extends its financial advantage
Johannesburg-based Standard Bank’s assets exceeded those of National Bank of Egypt by $34.29bn, or approximately 17 per cent.
Its official interim results showed total assets rising 12 per cent year on year to R3.808tn, while headline earnings increased 10 per cent to R26.1bn.
Return on equity improved from 19.1 to 19.8 per cent, while its common equity tier one capital ratio strengthened to 13.6 per cent.
The group also reported a decline in its credit loss ratio from 93 to 73 basis points, suggesting improved credit performance alongside balance-sheet expansion.
Standard Bank’s regional operations contributed 40 per cent of group headline earnings, demonstrating the importance of geographical diversification to its profitability.
Egypt’s largest lender holds second place
National Bank of Egypt ranked second, with assets equivalent to approximately 85 per cent of Standard Bank’s balance sheet.
Its scale reflects Egypt’s substantial domestic deposit market and the institution’s role in financing businesses and public investment.
However, comparisons expressed in dollars remain sensitive to exchange-rate movements. Depreciation of the Egyptian pound can reduce the international value of banking assets even when domestic-currency balances increase.
FirstRand, Absa and Nedbank reinforce South Africa’s dominance
FirstRand occupied third place in the First Bank ranking, with $167.31bn in assets.
Its consolidated financial statements reported assets rising from R2.589tn in June 2025 to R2.743tn in June 2026, an increase of approximately 6 per cent.
Absa followed with $139.23bn, supported by its South African banking franchise and operations across several African markets.
Nedbank completed the top five with $98.21bn, approximately $41bn below Absa and $134bn behind Standard Bank.
The differences illustrate the considerable variation in financial scale even among the continent’s leading lenders.
South Africa controls 76% of top-five banking assets
South African banks
$637bn
76.3% of combined assets
Egyptian bank
$198bn
23.7% of combined assets
The four South African banks collectively held approximately $637bn in assets, compared with National Bank of Egypt’s $198bn.
Their combined dominance reflects South Africa’s developed financial infrastructure, access to institutional capital and extensive banking networks.
Nevertheless, balance-sheet size is only one measure of banking strength. Profitability, capital adequacy, credit quality and operational efficiency provide a more comprehensive assessment of financial resilience.
Africa’s banking hierarchy remains dominated by South African institutions, but sustaining that advantage will depend increasingly on their ability to combine financial scale with profitability, disciplined lending and efficient capital allocation.