JPMorgan’s new frontier debt index puts Africa and Angola in global investors’ sights
- Economic
- September 14, 2026

Angola, Nigeria, Egypt and Morocco seek to turn domestic bond markets into a new source of international funding as investors weigh higher yields against currency and liquidity risks
LAGOS — A new JPMorgan index could bring billions of dollars of institutional capital closer to Africa’s local-currency bond markets, potentially reducing governments’ reliance on dollar-denominated external borrowing while deepening some of the continent’s thinnest capital markets.
The GBI-EM Edge, which JPMorgan is expected to launch by the end of September, will track about $330 billion of sovereign debt across 26 countries, with African markets accounting for roughly 45 per cent of the universe. The benchmark creates a new reference point for investors seeking higher returns in frontier economies, while accepting greater currency, liquidity and credit risks.
For Angola, the move comes at a strategic moment, the country is working to open its domestic government bond market to international investors and is seeking to meet the conditions for possible inclusion in the new benchmark.
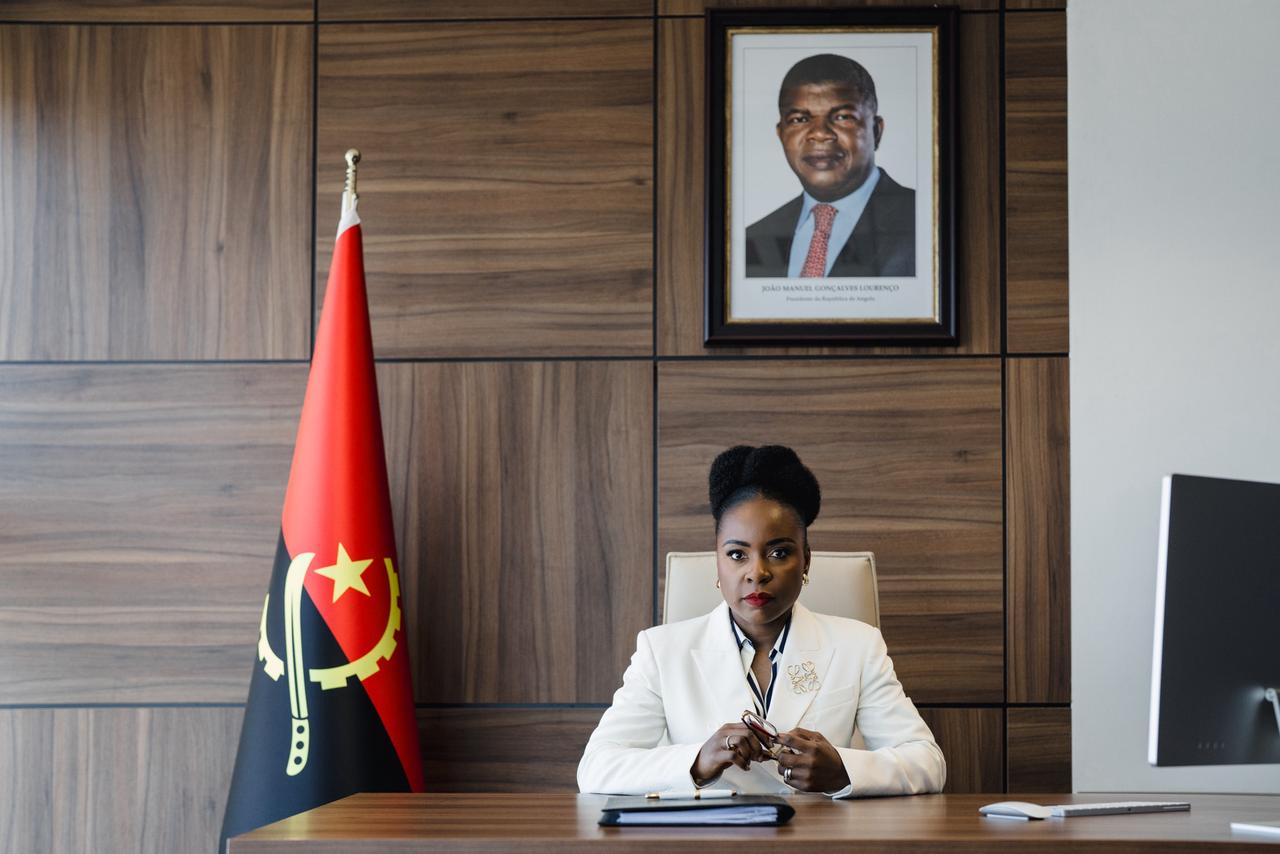
Vera Daves de Sousa, Angola’s Minister of Finance, has described the opening of the local debt market to foreign investors as part of efforts to deepen the country’s capital markets and broaden its investor base. Angola’s local government bond market was worth about $18.6 billion at the end of 2025, according to data released as part of the country’s efforts to attract foreign participation.
Index inclusion, however, does not automatically translate into capital inflows. Its importance lies in bringing a market into the investment universe monitored by global asset managers and potentially generating demand from funds that use the benchmark as a reference.
That distinction is particularly important for Angola.
A country can enter an index and still struggle to attract sustained foreign investment if investors face obstacles to buying securities, trading them in the secondary market or repatriating proceeds. To turn JPMorgan’s visibility into durable funding, Angola will need to continue improving market infrastructure, transparency, regulatory predictability and access for international investors.
The challenge is not unique to Angola, the new index comes as African governments seek to develop domestic bond markets capable of absorbing a larger share of public financing needs.
Egypt, Nigeria and Morocco are among the markets positioned to attract greater investor attention, while Kenya and other African economies are also seeking to deepen foreign participation in local markets. South Africa, with one of the continent’s deepest and most sophisticated capital markets, remains a benchmark for African local-currency debt.
Competition for global capital will therefore be about more than headline yields.
For an international investor, an Angolan government bond offering a high nominal yield may appear attractive. But that return is earned in local currency. A sharp depreciation of the kwanza can reduce — or even erase — the gain when the investment is converted back into dollars or euros.
That combination of high yield and high risk is precisely what makes frontier markets attractive to some institutional investors.
The GBI-EM Edge is expected to offer a portfolio of assets with higher yields than traditional emerging-market local-currency benchmarks. The index will also cap the weight of individual countries, limiting concentration and encouraging investors to look across a broader group of economies.
For African governments, however, the potential benefit extends beyond attracting foreign investors.
A deeper domestic bond market can improve price discovery, create a more reliable yield curve and provide a benchmark for companies seeking to issue debt. Over time, that could shift part of Africa’s financing away from banks and external creditors towards domestic capital markets.
It could also reduce a structural vulnerability.
Governments that rely heavily on dollar-denominated debt become more exposed to currency depreciation because the local-currency cost of servicing that debt rises when the domestic currency weakens. Issuing more debt in local currency does not eliminate macroeconomic risk, but it can reduce the direct exposure of public finances to swings in the dollar.
For Angola, that issue is particularly relevant given the importance of oil revenues and the economy’s sensitivity to crude prices and global financial conditions.
The potential index inclusion is therefore only the beginning.
International investors will look beyond bond yields to the stability of the kwanza, inflation, monetary policy, secondary-market liquidity, fiscal transparency and the ease with which capital can enter and leave the market.
The same applies across Africa. A new benchmark can put local bonds on the global investment map, but it cannot substitute for the reforms required to make those markets genuinely investable.
The opportunity is significant. For years, many African governments have relied on international eurobond markets to compensate for the limited depth of domestic capital markets. That provided access to hard currency, but also exposed public finances to dollar movements and abrupt shifts in global risk appetite.
The GBI-EM Edge offers a different proposition: bringing international capital into debt denominated in the currencies of the countries themselves.
For Angola, the question is no longer simply whether it can qualify for the index. The bigger test will be whether inclusion can translate into deeper liquidity, a broader investor base and a more efficient cost of government funding.
The index may open the door to global capital. The depth, predictability and credibility of domestic markets will determine whether investors stay.